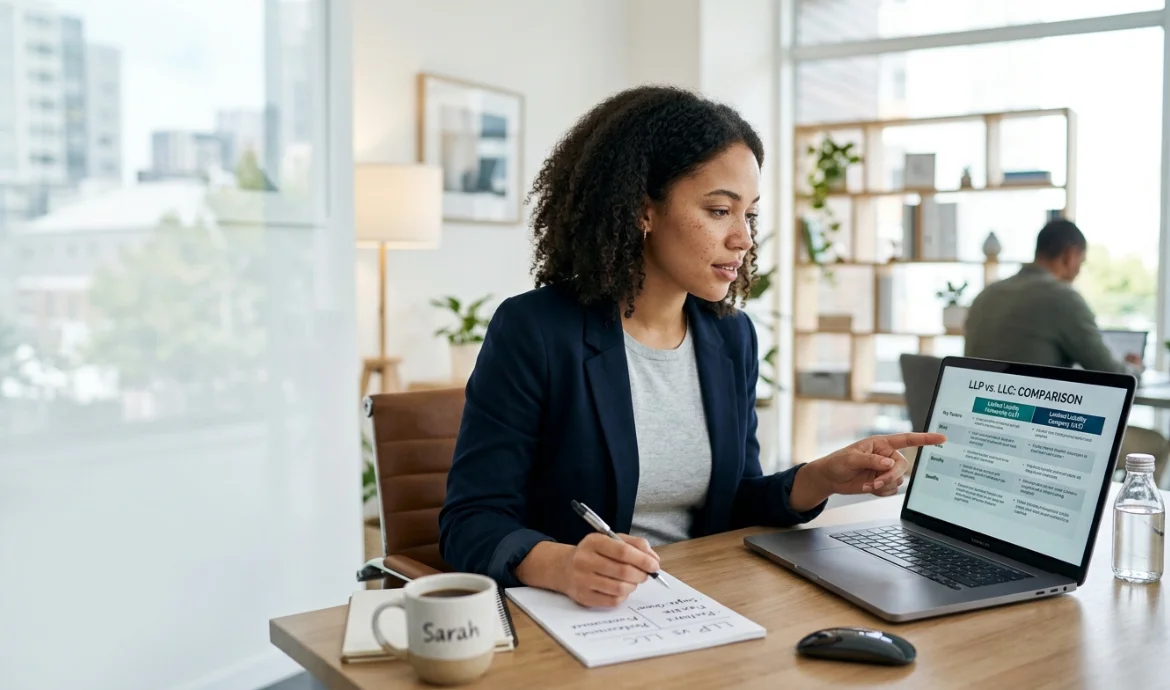
Choosing between these structures changes ownership, management, taxes, and the liability that may reach personal assets. The LLP vs LLC decision also depends heavily on state law. For most U.S. small businesses, the limited liability company is the more flexible starting point.
Short answer: Choose a limited liability company if you want one or more owners, flexible management, and broad state availability. Consider a limited liability partnership when two or more partners run a professional firm and state law allows it. Professional licensing rules can still change the answer.
Limited liability company and partnership compared
| Factor | Limited liability company | Limited liability partnership |
|---|---|---|
| Owners | One or more members | At least two partners |
| Availability | Broadly available under state LLC statutes | Availability and eligible professions vary by state |
| Liability | Members generally have protection from company debts | Partners generally receive protection from partnership obligations and other partners’ acts |
| Federal tax default | Single-member entities are usually disregarded; multi-member entities usually use partnership taxation | Partnership taxation generally applies by default |
| Tax elections | Corporate taxation may be elected when requirements are met | Certain partnerships can make federal classification elections, subject to tax consequences |
| Management | Member-managed or manager-managed | Usually partner-managed under the partnership agreement |
| Main strength | Flexible ownership, management, and federal tax classification | Partnership structure with liability protection for participating partners |
| Main tradeoff | State fees and professional-service restrictions may apply | Eligibility and liability rules vary more sharply between states |
| Common fit | Startups, operating businesses, property businesses, and many small companies | Law, accounting, architecture, and other qualifying professional firms |
Federal tax rules give a domestic company different default classifications based on its number of owners. State rules determine how the legal entity is formed and governed. Partnership liability rules also depend on the governing state statute.
LLP vs LLC: 7 differences that matter most
The seven differences below affect far more than the letters after your business name. They determine eligibility, control, tax filings, and possible exposure when problems arise. Your state and profession should therefore drive the final choice.
1. Ownership and eligibility work differently
A limited liability company may have one owner or several owners. The IRS calls those owners members and recognizes single-member entities. Members can also include individuals and other legal entities.
A limited liability partnership needs an underlying partnership, so one person cannot create one alone. State law can also restrict which businesses may register under this structure. Those restrictions make checking your state rules an essential first step.
2. Liability protection has different boundaries
A company member is generally not personally liable for entity debts merely because of ownership. That shield does not excuse the member’s own wrongful acts or a personal guarantee. State law may also create other exceptions to the liability shield.
A registered partnership can protect partners from partnership obligations and another partner’s acts. The IRS describes partners as generally protected solely because they hold partner status. The precise scope still depends on the applicable state statute. Professional malpractice deserves separate attention because entity protection does not erase personal responsibility for your own conduct. A lawyer, accountant, or architect can still face liability for personal professional negligence. Professional liability insurance therefore remains important regardless of entity choice.
3. Federal tax treatment is similar at first
A single-member domestic limited liability company is usually disregarded for federal income tax purposes. The IRS classifies a domestic company with at least 2 members as a partnership by default. The company can elect corporate classification instead when federal requirements are satisfied. A partnership generally files Form 1065 and reports each partner’s share through Schedule K-1. The partnership itself normally does not pay federal income tax on passed-through business income. Partners report their distributive shares on their own returns. Partners performing services are generally treated as self-employed rather than employees. Self-employment tax treatment can depend on the partner’s status and the income involved. Entity selection alone should therefore never substitute for tax planning.
A common online shortcut says partnerships can never elect corporate federal classification. That statement is too broad under the federal entity-classification rules. IRS Form 8832 states that eligible entities can include partnerships. Changing classification can still create significant tax consequences. An election may be treated as a transfer of assets followed by another deemed transaction. Have a qualified tax professional review the consequences before filing an election.
4. Management flexibility favors the company structure
Members can usually manage their company directly or appoint managers to handle operations. The operating agreement can divide authority, voting rights, and financial responsibilities. That flexibility works well when owners want different operational roles.
A partnership normally puts management rights in the hands of its partners. A written partnership agreement can adjust duties and decision rules within state-law limits. Clear drafting becomes especially important when several professionals share clients, employees, and expenses.
5. Professional-service rules can decide the question
California shows how strongly professional licensing can affect the choice. California permits registered limited liability partnerships for lawyers, architects, and accountants. Its rules also generally restrict ordinary limited liability companies from rendering licensed professional services.
Texas takes a different approach to the partnership structure. A general or limited partnership can register for limited liability status rather than creating a separate partnership entity. Texas also requires ongoing reporting to maintain that registration. Professional firms should check their licensing board alongside the secretary of state. Formation approval does not always answer professional-practice questions. Ventweek’s engineering consulting overview also provides useful context for owners building professional service businesses.
6. Formation and ongoing costs depend on the state
There is no reliable national filing price for either structure. States set formation charges, annual taxes, franchise taxes, and reporting fees independently. Two otherwise similar businesses can therefore face different costs because they operate in different states.
California generally imposes an $800 annual tax on registered limited liability partnerships. The California Franchise Tax Board confirms that every LLC doing business in the state owes an $800 annual tax, plus an income-based fee at specified levels. These rules make state costs part of the structural decision. Texas illustrates a different fee model for registered partnerships. Its LLP registration fee is $200 for each general partner. The required annual report also carries a $200 fee for each partner reported.
7. Future ownership plans can favor flexibility
A business with one founder cannot use a partnership structure requiring multiple partners. A company structure also allows owners to choose member management or appointed management. Those options can help when operational responsibilities change later.
Professional partnerships may prefer shared partner control instead. Their partnership agreement can address departures, new partners, voting, compensation, and succession. These provisions deserve attention before the firm signs major contracts or hires employees.
Which structure should you choose?
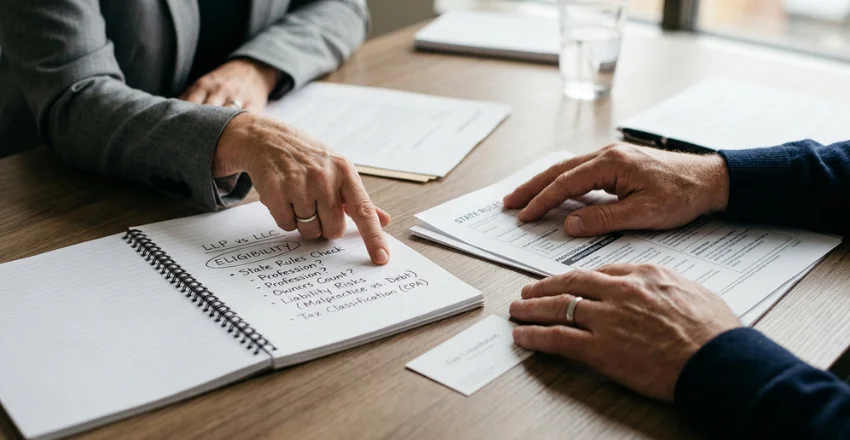
For a practical LLP vs LLC decision, start with eligibility rather than tax marketing claims. A general U.S. business will often find the company structure easier to fit around its ownership plans. A qualifying professional group may prefer a partnership structure that matches shared professional practice.
- Check your state’s eligibility rules first. Confirm whether your profession may use both structures in the state where you will practice.
- Count the owners. A solo founder can use a single-member company but cannot create a two-person partnership alone.
- Map the liability risks. Separate ordinary business debts, professional malpractice, personal guarantees, and each owner’s conduct.
- Review tax classification with a CPA. Compare default partnership treatment against any available corporate election before filing forms.
- Put governance in writing. Use a detailed operating agreement or partnership agreement covering authority, money, departures, and disputes.
Entity formation solves only one part of launching a business. You still need customer, budget, channel, and performance decisions after registration. Ventweek’s marketing plan template can help organize those commercial choices after the legal structure is settled.
Common mistakes to avoid
Choosing solely because one structure sounds more tax-efficient can create expensive problems. Federal classification and state-law entity status are separate questions. A tax election cannot fix an entity that your profession may not legally use. Another mistake is confusing a limited liability partnership with a limited partnership. A limited partnership usually separates general partners from limited partners with different roles. A limited liability partnership instead adds liability protection to an underlying partnership under state law.
Owners should also avoid assuming the entity shield covers every personal obligation. Personal guarantees, individual misconduct, and professional negligence can remain personal liabilities. Good contracts, insurance, accounting, and recordkeeping still matter after formation.
Make the choice from your state rules, not the acronym
Most general U.S. businesses should examine the limited liability company first because it supports solo or multiple ownership. Professional groups should compare that option against the partnership structures their state permits. A business attorney and tax adviser can confirm the choice before formation documents are filed.
After formation, document who controls decisions, how profits are distributed, and what happens when an owner leaves. Those terms often matter more than the entity label during a real dispute. For more startup and management resources, browse Ventweek’s business coverage before building the rest of your operating plan.
Frequently asked questions
Can one person form either structure?
One person can form a single-member limited liability company in most states. A limited liability partnership requires an underlying partnership, so it needs multiple partners. State professional rules may create additional requirements.
Is a limited liability partnership safer than a limited liability company?
Neither structure is universally safer in every situation. The better protection depends on the liability involved and the governing state statute. Your own wrongful conduct can still create personal exposure under either structure.
Do both structures use pass-through taxation?
Partnership taxation generally passes profits and losses through to partners rather than taxing the partnership itself. A multi-member limited liability company also receives partnership treatment by default. A company can choose another eligible federal classification through the required IRS election.
Is the LLP vs LLC choice the same in every U.S. state?
No, state rules can change eligibility, fees, reporting duties, and liability protection. California restricts registered partnerships to specified professions, while Texas uses an LLP registration for existing partnerships. Always check the current rules in your formation and operating states.
Which structure suits lawyers, accountants, and architects?
Professional firms should start with their state’s licensing and entity rules. California expressly allows lawyers, accountants, and architects to register qualifying limited liability partnerships. Other states may permit different professional entities or impose different ownership requirements.