If you’re asking when workers’ comp will offer a settlement, there is no single U.S. deadline. For most private-sector workers, state law governs the claim, settlement, and approval process.
Direct answer: A settlement offer often becomes more likely after your medical condition stabilizes and doctors can assess any lasting impairment. That point is commonly called maximum medical improvement, or MMI. Still, an offer can come earlier or later. State law, disputes, future treatment, and approval rules control the real timing.
| Question | Practical U.S. answer |
| Is there one national offer deadline? | No. State systems usually govern private-sector claims. |
| What commonly makes settlement easier to evaluate? | MMI, an impairment rating, work restrictions, and clearer future medical needs |
| Can an offer come before MMI? | It may, depending on the state and circumstances. |
| Does an accepted offer mean immediate payment? | No. Approval and payment can be separate stages. |
| Can medical benefits be closed by settlement? | In some states and settlement types, yes. Review future-care consequences carefully. |
Key Takeaways
- MMI is a common settlement milestone, but it isn’t a nationwide settlement deadline.
- An impairment rating can help define permanent disability after recovery stabilizes.
- Treatment, disputes, future medical costs, and Medicare issues can slow negotiations.
- State approval and payment rules can add time after the parties reach an agreement.
Why There Is No Single National Settlement Date
Workers’ compensation for employees of private companies and state or local governments is generally administered through state systems. If you are wondering when workers’ comp will offer a settlement, it is important to understand that the U.S. Department of Labor directs these workers to their state workers’ compensation agencies. That means a national promise such as “your insurer must offer within six months” can be misleading because settlement deadlines and procedures vary by state.
Tennessee shows why state-specific rules matter. Under circumstances described by its Bureau of Workers’ Compensation, an insurer should make a written settlement offer within 30 days after receiving the medical impairment rating. This is a Tennessee rule, not a nationwide deadline, so workers should check the specific laws and procedures that apply to their own workers’ compensation claim. What To Do If Your Workers’ Compensation Claim Is Denied? is a useful companion read here.
When Workers’ Comp Will Offer a Settlement? 7 Triggers to Watch
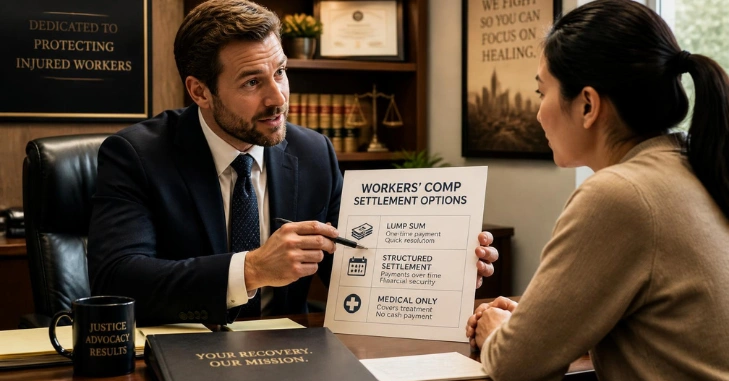
Insurers and injured workers need enough information to judge what a claim may require in the future. These seven developments can make serious settlement discussions more practical.
- You reach maximum medical improvement. MMI generally means your condition has healed as much as doctors expect at that stage. It doesn’t necessarily mean every symptom has disappeared.
- A permanent impairment rating is available. A treating physician may assign a rating after MMI. That rating can help determine permanent disability benefits under the applicable state system.
- Future treatment becomes clearer. The parties can better assess a settlement when the expected surgery, therapy, medication, or other care is known.
- Your long-term work status is clearer. Permanent restrictions or the ability to return to work can affect the issues remaining in the claim.
- Wage and benefit records are settled. Disagreements about earnings, disability periods, or unpaid benefits can make negotiations harder.
- Major medical or legal disputes have narrowed. Conflicting medical opinions and disputed claim issues can keep the parties far apart.
- Both sides are ready to trade future uncertainty for a final agreement. A settlement is negotiated. An offer alone doesn’t require you to accept it.
For related reading on why injury claims become harder to resolve, see VentWeek’s guide to factors that can make a personal injury claim complex. Workers’ compensation follows different rules, but medical disputes and documentation problems can create similar practical complications.
Can the Insurer Offer a Settlement Before MMI?
An early offer may be possible, depending on the state and the type of settlement. The main concern is uncertainty. Before recovery stabilizes, you may not know whether another procedure will be recommended. Permanent restrictions may also be unknown. A final impairment rating may not exist yet.
Closing future medical benefits can carry lasting consequences. New York’s Workers’ Compensation Board, for example, warns that a Section 32 settlement can permanently close the portions of a claim covered by the agreement. If medical care is settled, the worker may become responsible for future treatment costs. An early offer is therefore not automatically a good or bad offer. Its terms need to be compared with what remains uncertain.
What Can Delay a Settlement Offer?
A claim may remain open longer when important information is still changing or disputed.
Common sources of delay include:
- ongoing treatment or a planned surgery;
- disagreement over MMI or an impairment rating;
- disputes about whether an injury is covered;
- unclear permanent work restrictions;
- disagreement over wage or disability benefits;
- unresolved future medical costs; and
- Medicare-related issues in qualifying cases.
CMS states that parties resolving claims involving future medical expenses have responsibilities under Medicare Secondary Payer rules. A workers’ compensation Medicare set-aside can allocate part of a settlement for future injury-related treatment.
CMS guidance on Workers’ Compensation Medicare Set-Aside Arrangements does not require every proposed WCMSA to be submitted for review. Its current review criteria include certain settlements above $25,000 for Medicare beneficiaries. A second threshold applies when Medicare enrollment is reasonably expected within 30 months and the anticipated settlement exceeds $250,000.
Offer, Approval, and Payment Are Different Stages
One of the easiest mistakes is treating the first offer and the settlement check as the same event.
State procedures show how different the stages can be:
| State example | Offer or negotiation | Approval and payment |
| Tennessee | Certain cases call for a written offer within 30 days after the insurer receives an impairment rating. | Other state procedures still govern resolution. |
| California | You aren’t required to accept the claims administrator’s offer and may negotiate. | Settlements are reviewed by a workers’ compensation judge for adequacy. |
| New York | A Section 32 agreement is negotiated between the worker and the insurer. | After it becomes final, the insurer has 10 calendar days to have the settlement check postmarked. |
These examples aren’t interchangeable. Use the rules for the state handling your claim.
What to Check Before Accepting the First Offer
A dollar figure doesn’t tell you what rights the agreement closes.
Before signing, identify:
- whether the deal settles wage benefits, medical benefits, or both;
- What future treatment do your doctors expect
- whether an impairment rating is final or disputed;
- What permanent restrictions affect your work
- whether unpaid benefits or medical issues remain unresolved; and
- Whether Medicare interests need to be addressed.
California, for example, distinguishes settlements that preserve future medical care from compromises and releases that can place responsibility for future treatment on the worker.
If you’re considering professional help, VentWeek also has a guide on when legal representation may become useful after an accident. A workplace claim is legally different, so look for an attorney who handles workers’ compensation in your state.
What If the Insurance Company Never Makes an Offer
California expressly states that injured workers can negotiate rather than accept an administrator’s offer. If the parties cannot agree, a workers’ compensation judge can decide disputed benefits. Other states have their own hearing, conference, mediation, or adjudication procedures. Start by checking the agency that administers claims where you work. The Department of Labor maintains a directory of state workers’ compensation officials and agency websites. VentWeek’s Law section also includes broader explanations of claims, litigation, and legal processes
Your Next Step
Find the workers’ compensation agency for your state and check its settlement rules before relying on a national timeline. If you are researching when workers’ comp will offer a settlement, gather your latest medical report, impairment rating, work restrictions, benefit records, and the written offer if one exists. If the injury is serious, future treatment is uncertain, or the proposed agreement closes medical benefits, consider speaking with a workers’ compensation attorney licensed in your state before accepting or signing the agreement.
Frequently Asked Questions
There is no nationwide deadline. An offer often becomes easier to evaluate after your condition stabilizes, an impairment rating is available, and future treatment is clearer. Your state can impose additional rules or deadlines. Tennessee’s 30-day post-rating rule is one example.
No. MMI provides useful medical information, but a settlement still depends on state law, the issues in dispute, and whether the parties want to resolve the claim.
Settlement procedures vary by state. You don’t necessarily have to assume that only the insurer can raise the subject. California, for example, allows an injured worker to negotiate with the claims administrator.
There is no single national payment period. New York provides a useful example: in a final Section 32 agreement, the insurer generally has 10 calendar days to have the check postmarked. Other states use their own rules.
Don’t judge an offer by the lump sum alone. Review what benefits end, expected future medical care, permanent restrictions, and unresolved claim issues. If the agreement could close significant future benefits, consider getting state-specific legal advice before signing.